
 3 min read
 3
 Linkedin
 Threads
 Facebook
 X
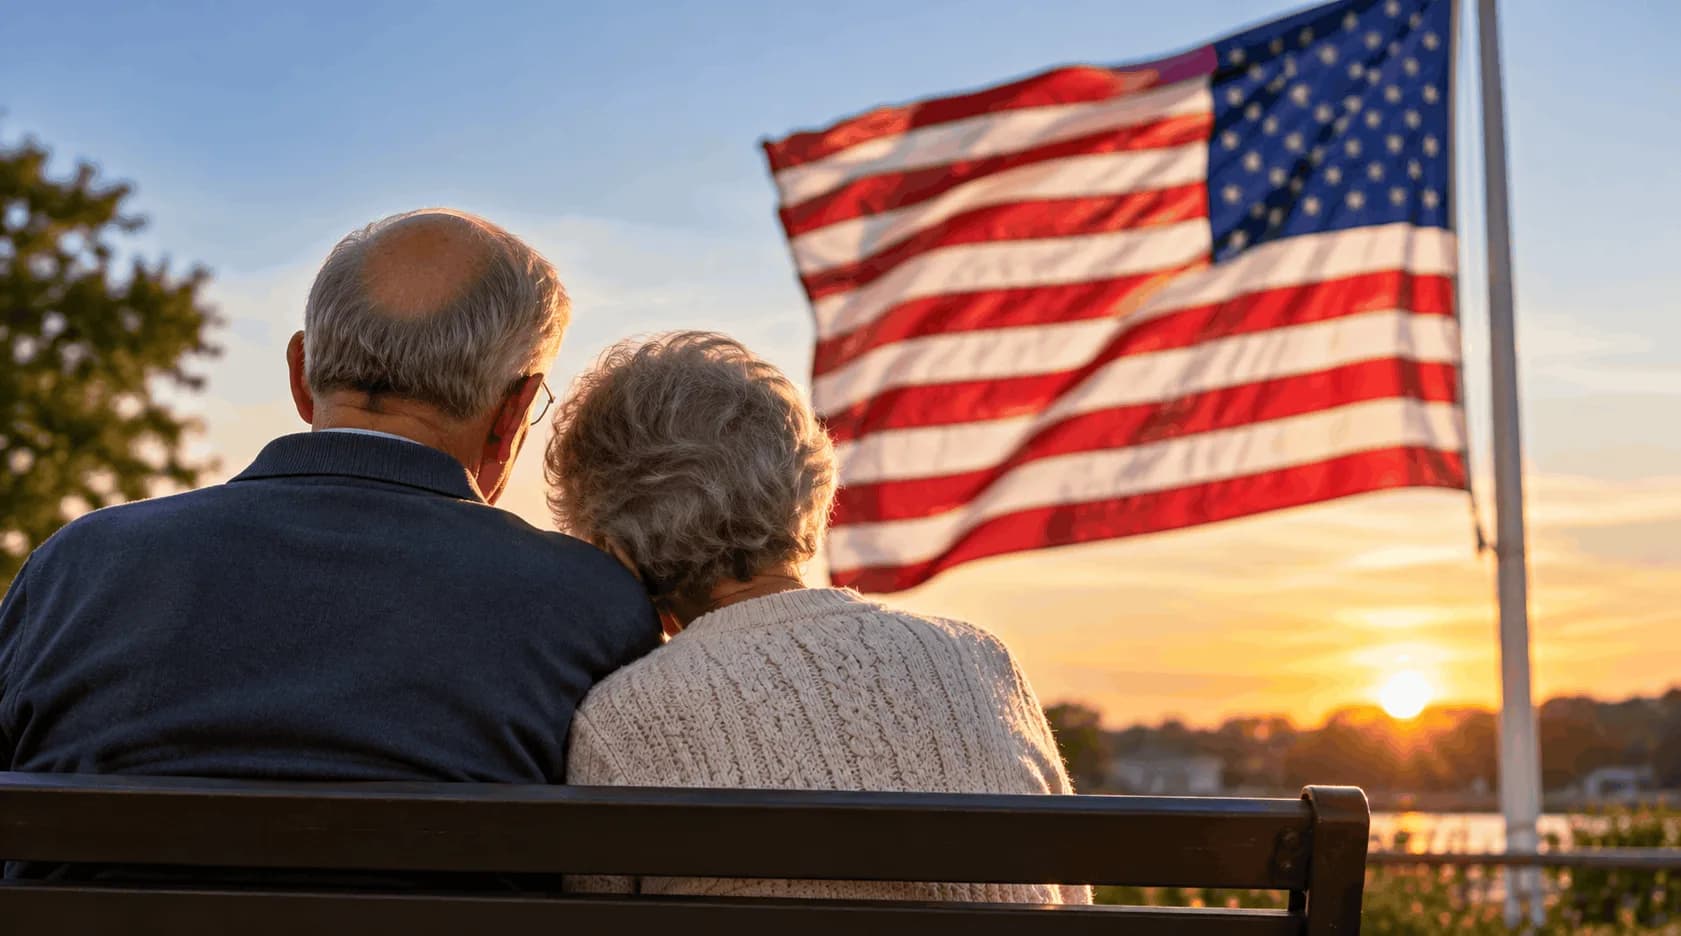
Millions of Americans approaching retirement face an important milestone in 2027: the full retirement age for Social Security will reach 67 for workers born in 1960, completing a gradual increase established by Congress more than four decades ago.
Under current Social Security rules, people born in 1959 reach full retirement age at 66 years and 10 months, while those born in 1960 or later must wait until 67 to qualify for their full retirement benefit.
The distinction can have lasting financial consequences.
A worker who begins collecting benefits at 62 may receive substantially smaller monthly payments than someone who waits until full retirement age. Delaying until 70 can increase those payments further.
But there is an important part of the story that can easily get lost in the headlines.
This is not a newly announced increase imposed for 2027. It is the final stage of a retirement-age schedule enacted in 1983.
And while that schedule is finally reaching its endpoint, a much larger debate is approaching: how America will finance Social Security as its population ages.
Why the Retirement Age Is Reaching 67
For much of Social Security's history, 65 was the standard age for receiving full retirement benefits.
That changed when Congress approved major amendments to the program in 1983.
The legislation gradually increased the full retirement age, reflecting longer life expectancies and concerns about the system's long-term finances.
Rather than increasing the age immediately, lawmakers established a phased schedule based on the year a worker was born.
For Americans born between 1943 and 1954, full retirement age remained 66.
For those born from 1955 through 1959, it increased in two-month increments.
People born in 1959 have a full retirement age of 66 years and 10 months. Those born in 1960 or later have a full retirement age of 67.
According to the Social Security Administration, the 1960 birth cohort begins reaching that milestone in 2027.
That does not mean everyone must continue working until 67.
It means 67 is the age at which eligible workers in that group can claim 100% of their calculated retirement benefit without a reduction for claiming early.
And that difference is where the financial stakes become significant.
The Difference Between Retiring at 62, 67, and 70
Social Security offers workers flexibility in choosing when to begin receiving retirement benefits.
For most eligible workers, the earliest claiming age is 62.
However, collecting at that age permanently reduces the starting monthly benefit compared with waiting until full retirement age.
For someone whose full retirement age is 67, claiming at 62 results in a 30% reduction.
Waiting until 67 provides 100% of the worker's full retirement benefit.
Delaying until 70 increases the monthly benefit through delayed retirement credits, producing approximately 124% of the full retirement amount.
Consider a hypothetical worker entitled to $2,000 per month at full retirement age.
Age benefits begin - Illustrative monthly payment
62 - $1,40067
67 - $2,00070
70 - $2,480
These examples assume a full retirement age of 67 and exclude future cost-of-living adjustments and other individual factors.
The difference between claiming at 62 and waiting until 70 is $1,080 per month, or $12,960 annually.
That is not a small decision for a household managing housing payments, groceries, prescriptions, insurance, and other retirement expenses.
However, waiting longer also means receiving fewer years of payments.
Someone who collects benefits at 62 receives income during years when another worker may still be waiting.
The best decision therefore depends on more than maximizing a monthly check.
Health, family circumstances, employment opportunities, savings, and expected longevity all play a role.
Why Claiming Early Can Be Both Helpful and Costly
For some Americans, retiring at 62 is not simply a lifestyle preference.
A physically demanding job may become increasingly difficult with age. Health problems can interrupt employment. Layoffs or family caregiving responsibilities may make continued work impractical.
In those situations, Social Security can provide essential income before full retirement age.
But accepting a reduced benefit can also create long-term financial pressure.
Imagine a retiree who claims early because an immediate paycheck is necessary.
That choice may provide financial stability today, even though the smaller monthly benefit could become more difficult to live on as housing, healthcare, and other expenses change.
For another worker with adequate savings, postponing benefits may create a stronger source of guaranteed monthly income later in life.
There is no single claiming age that produces the best outcome for every household.
The important question is not simply how much money a person can receive next month. It is how that decision affects financial security over the decades ahead.
Retirement and Medicare Are Two Different Decisions
Another common source of confusion involves Medicare.
Social Security's full retirement age is reaching 67, but Medicare eligibility generally continues to begin at 65.
That distinction matters for people who plan to delay retirement benefits.
A worker who waits until 67 or 70 to collect Social Security may still need to enroll in Medicare at 65, depending on their existing health coverage.
Certain individuals can qualify for special enrollment periods, including those covered by qualifying employer health insurance.
Others may face late-enrollment penalties if they miss applicable deadlines.
Therefore, delaying Social Security benefits should not automatically mean delaying decisions about Medicare.
Workers approaching 65 should review their healthcare coverage separately from their retirement-income strategy.
The Bigger Problem: Social Security's Financial Future
The scheduled increase to 67 is only one part of a much larger demographic challenge.
America has an aging population, and Social Security depends substantially on payroll taxes collected from current workers to finance benefits for current retirees.
As the population ages, the relationship between workers contributing to the system and retirees receiving benefits becomes increasingly important.
The Social Security Board of Trustees' 2026 report projects that the Old-Age and Survivors Insurance Trust Fund will exhaust its reserves in the fourth quarter of 2032 under current law.
At that point, continuing income would be sufficient to cover approximately 78% of scheduled retirement and survivor benefits if Congress made no changes.
That does not mean Social Security payments would disappear.
Payroll tax revenue would continue flowing into the program.
But the projections demonstrate that scheduled benefits exceed the financing currently expected to support them.
If the retirement and disability trust funds were combined, the trustees project reserve depletion in 2034, with continuing income covering approximately 83% of scheduled benefits at that point.
These are financial projections, not already enacted benefit reductions.
Congress could change taxes, benefits, retirement rules, or other aspects of the program before those dates.
And that is where the debate becomes more complicated.
Some policymakers favor increasing revenues to strengthen Social Security's finances. Others emphasize changing future benefit formulas, adjusting eligibility rules, or combining different approaches.
Each option affects workers, retirees, employers, or taxpayers differently.
The challenge is preserving adequate retirement income while financing the promises made to future generations.
What Americans Approaching Retirement Should Do Now
For someone planning to retire in 2027 or shortly afterward, the most useful step is to understand how the rules apply to their own circumstances.
The Social Security Administration provides personalized benefit estimates through its online my Social Security service.
Workers can review their earnings history, estimate benefits at different claiming ages, and examine how continued employment may change future payments.
There are several practical factors worth evaluating before making a decision.
First, compare the estimated monthly benefit at 62, full retirement age, and 70.
Second, consider whether employment income, pensions, investments, or other resources can cover expenses if Social Security payments are delayed.
Third, remember that claiming Social Security before full retirement age while continuing to work can trigger temporary benefit withholding if earnings exceed the applicable annual limit. Those limits are adjusted periodically.
Finally, review how retirement timing may affect a spouse or surviving family member.
A claiming decision can influence more than one person's financial future.
Official benefit estimates and retirement planning resources are available at www.ssa.gov/myaccount/.
Retirement Is Becoming a Bigger Financial Decision
The arrival of the full retirement age of 67 in 2027 marks the completion of a policy change set in motion more than forty years ago.
But for millions of American families, the implications are very current.
Workers are balancing longer life expectancies against healthcare expenses, housing costs, uncertain employment, and the possibility of spending several decades in retirement.
For someone who has worked since their teenage years, the difference between claiming at 62 and waiting until 67 may mean five additional years before receiving full benefits.
For another person, delaying until 70 could provide greater monthly financial security during advanced age.
Neither decision can be evaluated through the retirement-age number alone.
And with Social Security facing a significant long-term financing challenge, future policy decisions in Washington will matter almost as much as individual planning.
The new milestone should encourage Americans to examine what retirement actually means for their household.
Because the most important retirement number is not necessarily the age when a person stops working. It is the income they can depend on when the paychecks stop.